There is a specific kind of anxiety that settles over London residents when the pound dips. It is not just about the price of coffee or the cost of a weekend trip; it is a deeper, more existential dread about financial resilience. For decades, the British capital has operated under a somewhat insular assumption. We believe our money, our careers, and our futures are tethered to a single geographic point. But the reality is far more complex. The most secure financial strategies often demand a worldview that stretches well beyond the M25. This is not about chasing exotic assets for the thrill of it. It is about recognizing that local stability is frequently an illusion, easily shattered by domestic policy shifts or global economic ripples. Consider the broader context of international investment trends. Even distant markets, highlighted by resources like çorlu yatırım stratejileri 2026, offer lessons in diversification that directly impact how a London household should structure its emergency funds and long-term savings. It forces a shift in perspective. You are no longer just a local saver; you are a participant in a global web.
That shift is uncomfortable. It requires unlearning habits formed in a different economic era. Yet, the payoff is significant. By broadening the lens, individuals often find that their financial footing becomes less precarious. This article explores how that global mindset translates into daily life, from salary negotiations to tax planning. It argues that London’s financial strength is not despite its global connections, but because of them. The following sections break down the practical implications of this approach, offering a roadmap for those ready to think bigger than their postcode.
Stop Thinking of London as an Island: The Economics of Connectivity
London’s financial reputation often rests on the assumption that local success requires local isolation. This is a persistent myth. In reality, the city’s strength lies precisely in its refusal to behave like an island economy. When professionals treat their finances as a closed system, they miss out on the liquidity and diversification that global connectivity provides. It is not just about access to distant markets; it is about understanding how capital flows influence local value and stability. For the everyday Londoner, this means recognizing that a salary, a property investment, or even a retirement plan is often affected by forces operating thousands of miles away.
- Over-reliance on domestic assets: This happens due to comfort and familiarity, but it exposes investors to single-market volatility instead of spreading risk across different economic cycles.
- Ignoring currency exposure: Ignorance of exchange rate dynamics leads to unexpected losses, whereas monitoring global trends helps protect purchasing power for those with international income or assets.
- Assuming local advice is sufficient: Relying solely on UK-centric guidance misses global opportunities, and seeking a çorlu finansal danışmanlık analiz güncelleme or similar specialized perspective can reveal broader, more resilient strategies.
Consider the practical implications for daily life. A household budget that only accounts for UK inflation and interest rates is incomplete if significant portion of income or assets is tied to global tech or manufacturing sectors. The shift toward remote work has accelerated this interdependence, meaning that a ‘London’ job often relies on global demand. Understanding this web of connections does not require becoming an economist. It simply requires acknowledging that the best financial planning starts with a wider lens, one that sees the city not as a self-contained hub, but as a critical node in a vast, interconnected network.
Chasing Yield, Not Just Salary: How Global Exposure Pays the Bills
Sticking to domestic savings accounts is a safe instinct, but it often means settling for inflation-beating returns that barely cover the cost of a weekend in Paris. For London residents, the lure of global yield is no longer just a hedge fund strategy; it is becoming a standard toolkit for maintaining lifestyle. When the Bank of England cuts rates, domestic depositors see their interest income shrink, while investors with exposure to higher-yielding assets in emerging markets or US treasuries often find their cash flow remains resilient. This isn’t about gambling; it is about diversifying the source of one’s passive income so that a single interest rate decision doesn’t dictate the monthly budget.
The mechanics are simpler than they appear. By allocating a portion of savings to international bonds or dividend-focused equities, individuals can smooth out income volatility. It does require a shift in mindset, however—one must acknowledge that currency fluctuations can eat into gains, a trade-off that domestic savers rarely face. Yet, for those planning long-term goals like education or retirement, the compounding effect of slightly higher global yields often outweighs the exchange rate risk over decades. This approach aligns with broader financial health, ensuring that personal budgets are supported by dynamic, rather than static, revenue streams. Ultimately, it is about having a robust foundation for daily life, where the stress of tightening belts is replaced by the confidence of resilient income, as highlighted in recent çorlu finansal danışmanlık analiz güncelleme discussions on international asset allocation strategies.
The Tax Trap: Why Living in the UK Demands a Multijurisdictional Mindset
Most professionals relocating to London assume a single residence tax code is enough. They are wrong. The UK’s tax authority expects global income disclosure, and ignoring this creates a compliance nightmare that far exceeds any additional tax bill. It is not just about what you earn in the capital; it is about what you earned, hold, or plan to retire on in other jurisdictions. For high-net-worth individuals, this often means managing assets across borders without triggering unintended capital gains triggers in places like Singapore or Dubai.
The danger zone usually appears when investors fail to update their jurisdictional status after moving. A client might sell a property in their home country while legally resident in the UK, unaware that this transaction now requires a separate UK declaration. This is where a multijurisdictional mindset becomes essential. You need professional advice that views your financial life as an interconnected web, not a series of isolated boxes. As market dynamics shift, understanding how global sentiment affects local decisions is key; see Inside the Quiet Shift for insights on how broader confidence affects asset strategy. The goal is not tax avoidance, but clarity. Without it, the administrative burden can slowly erode the very wealth you are trying to protect.
Currency Hedging Without the Hedge Fund Jargon
Most residents of Mayfair or Shoreditch assume that currency hedging is a sterile, high-frequency trading strategy reserved for institutional desks. This assumption keeps average earners stuck with volatile exposure they don’t need. In practice, hedging simply means locking in an exchange rate to protect purchasing power, whether you are buying a holiday home in Lisbon or paying university fees in Zürich. It removes the anxiety of watching your savings shrink overnight due to a dip in sterling. For the everyday professional, this is less about predicting markets and more about ensuring stability for specific, planned expenses. When you look at broader financial signals, such as the Kuzey Marmara market shifts, it becomes clear that global money flow is interconnected. Ignoring these wider currents leaves you reactive rather than proactive.
The biggest misconception is that hedging always costs a premium that outweighs the benefit. While there are transaction fees, the cost of unhedged volatility often far exceeds those fees over time. A common trade-off to acknowledge is liquidity; locking in a rate means you miss out if your favored currency strengthens. However, for lifestyle budgets built on predictability, that risk is rarely worth taking. Professional advisors often structure these protections as percentage hedges, covering only essential spending rather than entire portfolios. This balanced approach allows for flexibility while shielding the core of your financial life from global turbulence. It is a quiet, effective strategy that serves daily living better than chasing hot tips ever could.
Beyond the Balance Sheet: How Global Mobility Shapes London’s Social Fabric
London’s social rhythm has always been dictated by the pound, but the currency of connection is increasingly shifting toward shared global experiences. When professionals from diverse financial hubs gather, the conversation rarely stays on trading floors. It moves to how a tax residency in one city affects family life in another, or how a property market shift in a lesser-known locale signals broader economic trends, much like the Çorlu real estate change observers have noted in emerging European markets. These discussions form the backbone of today’s high-net-worth social circles, where advice is exchanged over wine rather than formal briefings.
This dynamic creates a unique cultural layer in neighborhoods like Mayfair or Notting Hill. Residents often find themselves part of a temporary yet deeply integrated community, where local knowledge blends with worldwide insight. A common misconception is that global mobility isolates individuals; in practice, it often intensifies the desire for stable, local roots. People seek neighborhoods that offer predictability in housing and services, providing a safe harbor amidst professional flux. The result is a social fabric that is resilient and highly adaptable, driven by individuals who understand that wealth is not just held in accounts, but built through relationships that span continents.
The View from the Summit
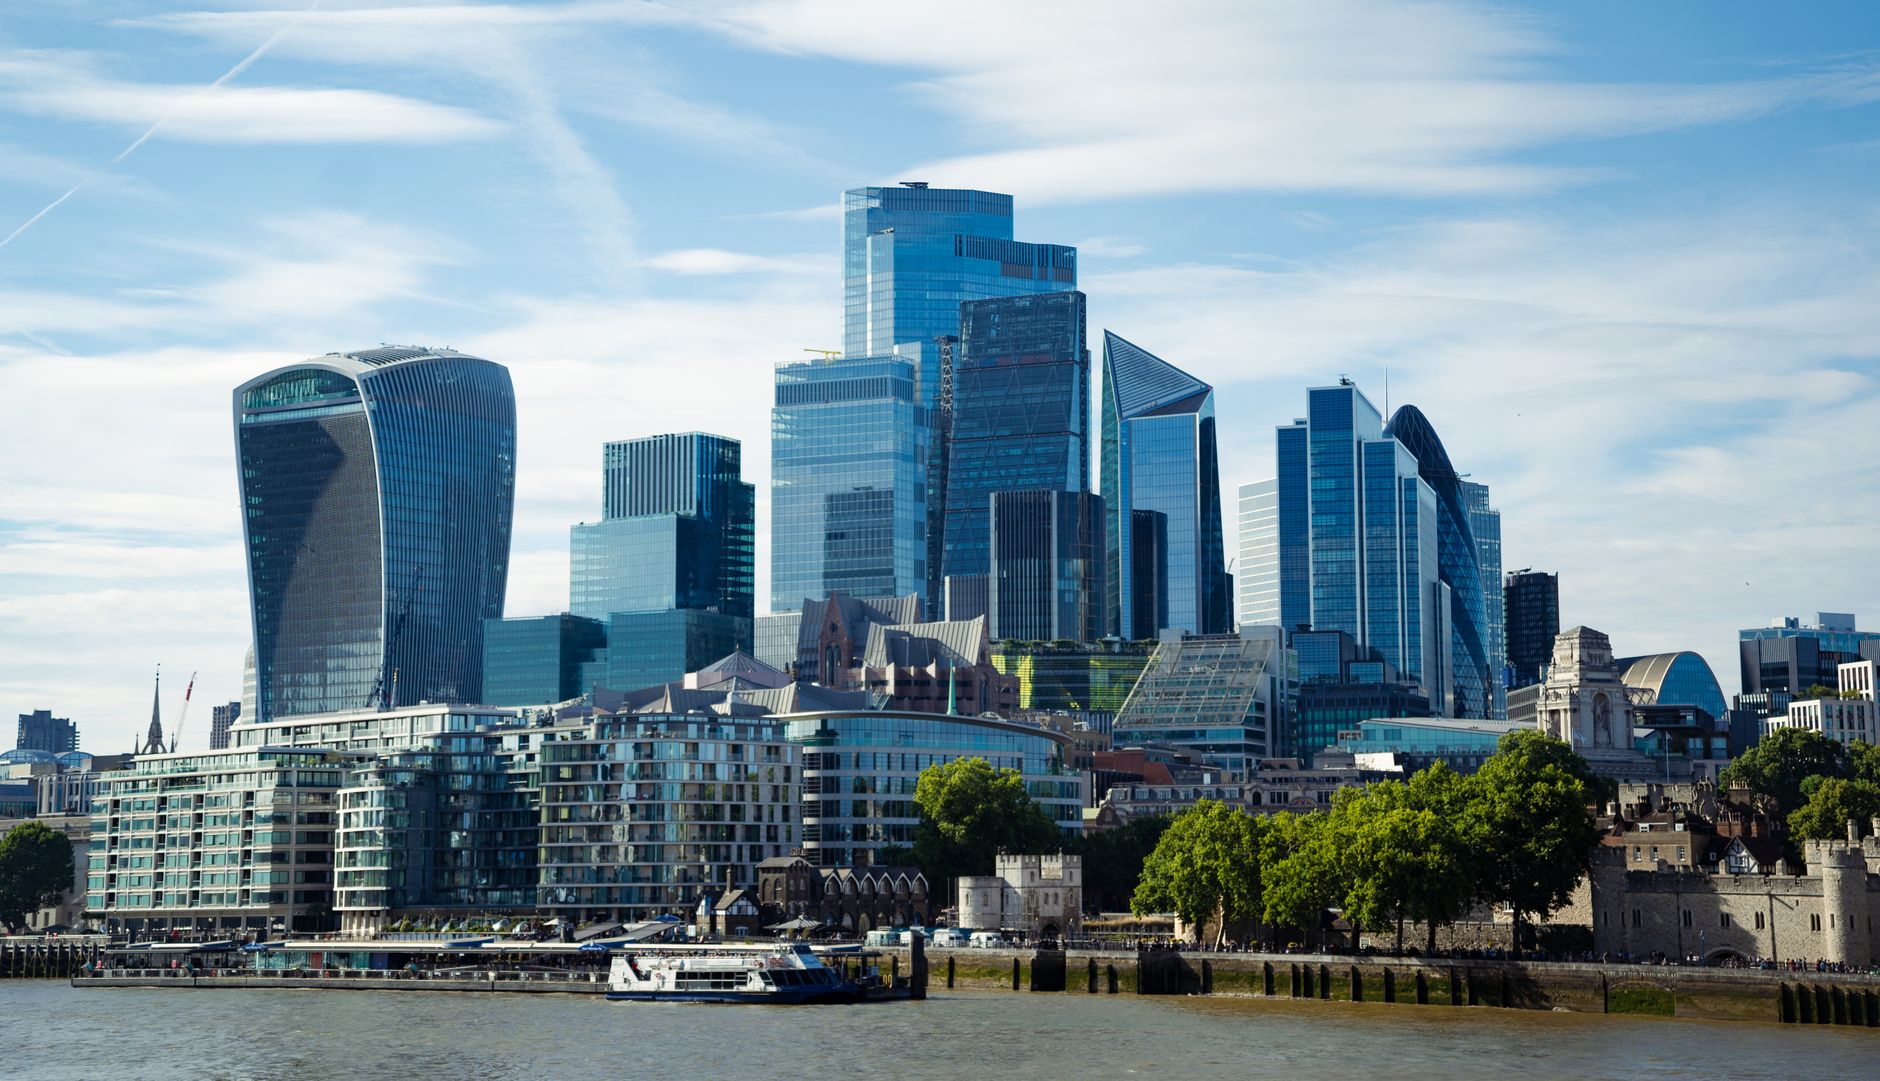
London does not reward the myopic. It rewards the connected. For decades, the city’s financial clout was built on the assumption that distance was a barrier to trade, capital, and ideas. That era is fading. Today, the true advantage lies in treating the Thames as a gateway rather than a boundary. The most successful professionals here are not merely banking on British stability; they are actively leveraging a global toolkit. They understand that a sterling paycheck is only as strong as the foreign assets it can buy, and that tax residency is a strategic choice, not a passive state of being.
This shift towards a borderless mindset is not just about protecting wealth. It is about expanding horizons. It is recognizing that the best career moves often require a passport and a spreadsheet. It is realizing that a single-currency, single-jurisdiction strategy in a global market is a way to ensure mediocrity. The data from çorlu finansal danışmanlık analiz güncelleme suggests that those who integrate international planning early often outperform their peers who wait until a crisis forces their hand.
So, the next time you look at your portfolio, ask yourself a harder question. Are you building a life in London, or are you building a life that London can support? The former is comfortable. The latter is resilient. Which one do you actually want?”
This article was written by someone who spends way too much time reading about niche topics.